
Latest posts
-
Equatorial Guinea: Corporate Tax Compliance
Companies follow a calendar year for corporate income tax (CIT), with each accounting period running from January through December. Filing and Payment Deadlines Businesses generally have six months after the financial year closes to submit their CIT returns. An exception applied to 2024 returns, which were due on 30 April 2025. CIT payments must reach…
-
Filing Deadlines, Payments, Penalties and Appeals for Corporate Tax in Egypt

Egyptian companies calculate their tax liabilities using their own financial year. Each business must establish the amount owed, prepare its annual corporate income tax return, and pay any outstanding balance when submitting it. The filing deadline falls four months after the accounting year closes. For businesses whose year ends on 31 December, submission is therefore…
-
Cameroon Corporate Tax Guide: Filing Deadlines, Payments And Audit Rules
The tax year in Cameroon runs from January to December. Businesses must prepare annual returns using OHADA accounting standards, with filing deadlines determined by their supervising tax office. Large taxpayers file by 15 March, medium and specialised centre taxpayers by 15 April, and divisional centre taxpayers by 15 May. Outstanding corporate income tax falls due…
-
Botswana’s Corporate Tax Filing Deadlines, Payments And BURS Rules
Corporate tax compliance in Botswana depends on keeping reliable records, observing filing deadlines, and planning payments throughout the business year. The system places responsibility on companies to calculate their taxable income and disclose it correctly. Understanding how these obligations fit together helps businesses manage cash flow and avoid unnecessary administrative pressure. Choosing the Accounting Period…
-
Angola Corporate Tax Compliance: Filing Deadlines, E-Invoicing And Penalties Explained
Corporate tax compliance in Angola requires businesses to coordinate annual reporting, advance payments, invoicing and correspondence with the tax authorities. Since the tax year runs from January through December, finance teams should build their compliance calendar around both year end accounts and obligations arising throughout the year. Filing Returns and Settling Liabilities Companies within the…
-
Uganda Corporate Income Tax Guide: 30% Rate, Small Business Rules & Examples
Understanding Uganda’s corporate tax framework helps businesses assess expansion costs, maintain records, and anticipate liabilities. Resident companies are taxed on worldwide income. Nonresident companies pay Ugandan income tax only on earnings sourced within Uganda. For example, a Ugandan coffee exporter must consider income from regional sales when assessing its taxable income. Calculating Corporate Tax The…
-
Corporate Income Tax (CIT) in Tunisia

A company’s exposure to Tunisian corporate income tax depends on where its income arises and how its activities are organised. Resident businesses are taxed on profits from Tunisian permanent establishments and amounts assigned to Tunisia under applicable tax treaties. Foreign companies face taxation on Tunisian income, including withholding taxes where no local establishment exists. Foreign…
-
Tanzania Corporate Tax Guide: Rates, Business Incentives And Minimum Tax Explained
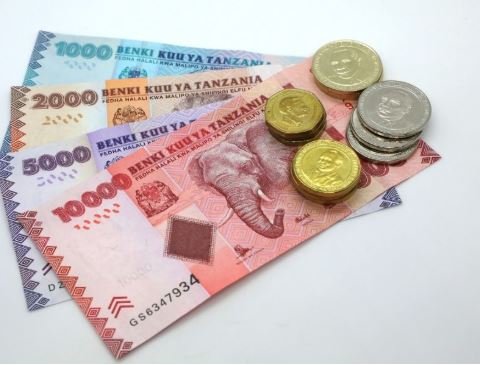
In Tanzania resident companies are taxed on earnings generated both locally and overseas. Nonresident businesses are taxed on income sourced within Tanzania. The standard corporate income tax rate is 30%, including for Tanzanian permanent establishments of foreign companies. Technical and management service providers serving mining, oil and gas businesses face a separate charge of 10%…
-
South Africa Corporate Tax Guide: Company Rates, Small Business Relief And Dividend Rules
For businesses operating in South Africa, tax exposure depends on residence. Resident companies generally account for income earned locally and abroad, while foreign companies face tax on income sourced within South Africa. The standard corporate income tax rate is 27%, applying to assessment years ending from 31 March 2023 onward. Previously, the rate was 28%.…
-
Borrowing to Move a Business Forward
A growing business can have strong demand and still lack the money needed to fulfil orders, replace machinery or open another location. Debt financing bridges that gap by providing funds that must be repaid under agreed conditions. Instead of selling part of the business, owners borrow from a lender or raise money from investors who…