
Did you know that Botswana follows a territorial approach to personal income tax? In practical terms, tax is generally determined by the source of income rather than simply an individual’s nationality. Income arising from employment, business activities or other taxable sources within Botswana may therefore be subject to tax in the country.
Work performed outside Botswana can still be regarded as Botswana-sourced when those duties are incidental to employment based in Botswana. This can affect employees who occasionally travel abroad while continuing to perform responsibilities connected to their Botswana employment.
Income Tax for Residents in Botswana
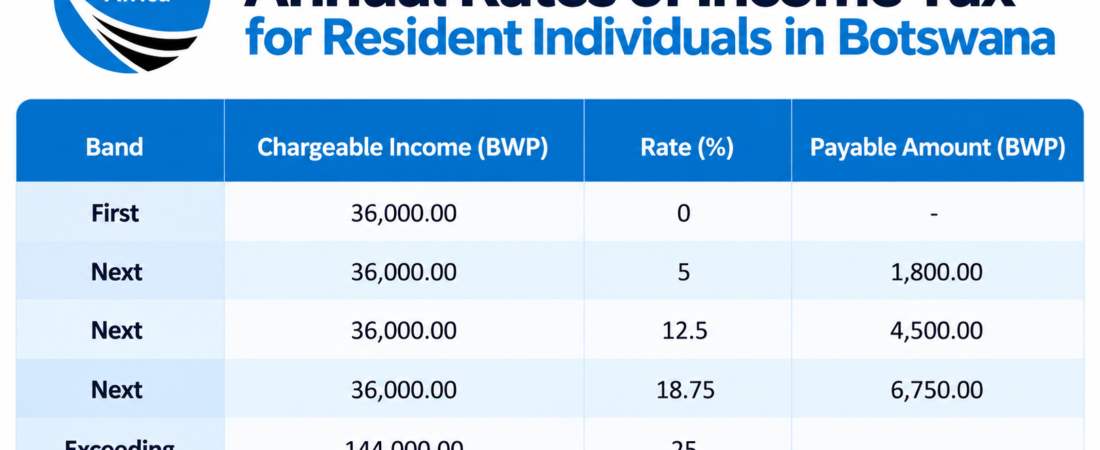
Resident individuals are generally taxed on income arising from Botswana sources. Personal income tax operates progressively, meaning different portions of taxable income are taxed at different rates.

For example, assume Naledi has annual taxable income of BWP 180,000. The first BWP 144,000 results in tax of BWP 13,050. The remaining BWP 36,000 is taxed at 25%, producing BWP 9,000. Her total annual income tax would therefore be BWP 22,050.
Source: Botswana Unified Revenue Service
Tax Treatment of Non-Residents
Non-residents earning taxable Botswana-sourced income are subject to a different starting structure.
Withholding Tax on Certain Income
Some Botswana-sourced payments received by non-residents are subject to withholding tax. Interest, commercial royalties, and management or consultancy fees generally attract 15%, while dividends and entertainment fees are generally subject to 10%.
For example, a BWP 40,000 qualifying consultancy payment subject to 15% withholding tax would result in BWP 6,000 being withheld.
Read Also: Withholding Tax in Botswana
Local Income Taxes
Botswana does not impose an additional local income tax alongside the central personal income tax system. Individuals should therefore focus on their residency position, income source, applicable tax band and any relevant withholding obligations when estimating their Botswana tax liability.
Frequently Questions and Answers about Personal Income Tax in Botswana
How does personal income tax work in Botswana?
The country mainly uses a territorial tax system. Individuals are generally taxed on income sourced within Botswana, subject to the applicable personal income tax rules.
Do Botswana residents receive a tax-free income band?
Yes. Under the tax bands covered in this guide, resident individuals pay no tax on the first BWP 48,000 of annual taxable income.
Are non-residents taxed differently from residents?
Yes. Non-residents do not receive the same tax-free starting band. Their Botswana-sourced taxable income begins at a 5% rate, with higher rates applying progressively.
What is the highest personal income tax rate for residents in Botswana?
The highest rate shown in the individual tax bands is 25%. It applies to the portion of annual taxable income exceeding BWP 144,000.
Does withholding tax apply to non-residents?
Yes. Certain Botswana-sourced payments to non-residents may attract withholding tax. Examples include dividends, interest, commercial royalties, consultancy fees and entertainment fees.
Does Botswana charge additional local income tax?
No. There is no separate local income tax imposed on individuals in addition to the central government income tax covered in this guide.