
Latest posts
-
Rwanda’s Corporate Income Tax System
Rwanda applies a combination of source-based and residence-based taxation to businesses. Companies earning income from activities within the country are generally subject to Rwandan tax, while resident businesses must also declare income generated abroad. Where foreign income has already been taxed overseas, a tax credit may be available, limited to the amount of Rwandan tax…
-
Nigeria’s Corporate Income Tax Framework

Nigeria is one of Africa’s biggest economies, and its corporate taxation system determines how businesses contribute to government revenue based on their earnings, activities, and size. Resident companies are generally taxed on worldwide income, whereas foreign businesses are taxed on income connected to Nigeria. Large companies face a 30% corporate income tax (CIT) rate, while…
-
Namibia Corporate Income Tax (CIT): Latest Tax Rates, Exemptions, Deductions & Foreign Company Rules
Namibia’s territorial taxation framework implies that businesses generally pay corporate income tax on earnings obtained within the country. Revenue considered to originate from Namibia may also be taxable, regardless of where the receiving company is headquartered. However, certain income categories qualify for exemptions under national tax legislation. Tax Responsibilities for Foreign Businesses International companies conducting…
-
Corporate Income Tax (CIT) in Mozambique
For corporate income tax in Mozambique, the country runs a system that distinguishes between businesses established locally and foreign companies earning revenue within its borders. Tax obligations depend largely on residency, business presence, and the nature of income generated. Taxation of Resident Companies Companies classified as Mozambican tax residents must declare income earned both domestically…
-
Morocco Corporate Tax Rates: Complete Guide to CIT, Tax Exemptions and Business Regulations

Morocco’s corporate taxation system generally targets profits and capital gains arising within its borders. Businesses calculate their taxable earnings by subtracting allowable operating expenses from revenue. Costs directly associated with commercial activities are usually deductible, provided they satisfy applicable tax requirements. Corporate Tax Rates for 2026 Morocco applies two principal corporate income tax (CIT) rates,…
-
Corporate Income Tax (CIT) in Mauritius: Rates, Regulations and Business Obligations
Mauritius offers a corporate taxation framework that combines competitive tax rates with specific incentives for international businesses and selected industries. Companies operating in the country must understand how their residency, business activities and earnings influence their tax obligations. Corporate Tax Rates and Residency Rules The standard corporate income tax rate in Mauritius is 15% of…
-
Corporate Income Tax (CIT) in Mauritania
Mauritania’s territorial corporate taxation system means businesses generally pay tax on profits generated within the country. Earnings from activities conducted entirely abroad are ordinarily excluded. However, income earned through Mauritanian operations remains taxable, regardless of whether the company is locally owned or foreign-controlled. Revenue from goods and services exported by Mauritanian businesses also falls within…
-
Taxation for Companies in Madagascar
In Madagascar, the corporate taxation system considers a business residency, annual revenue, and the nature of commercial activities. Companies established in the country generally pay tax on income earned domestically and internationally, while foreign businesses face taxation on qualifying Madagascar-sourced earnings. Corporate Tax Rates for Resident Companies Businesses generating annual turnover below MGA 400 million…
-
Corporate Income Tax (CIT) in Libya
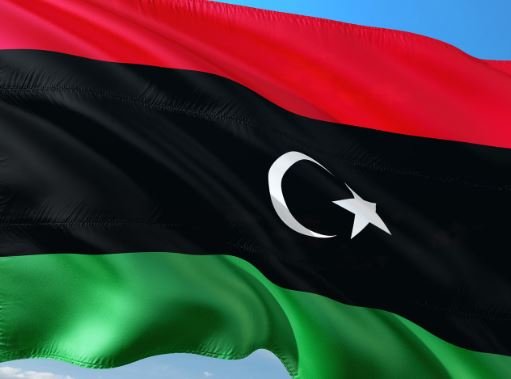
ibya imposes corporate income tax (CIT) on taxable business profits, with a standard rate of 20%. Companies registered in Libya are generally required to account for income earned both domestically and internationally when determining their annual tax obligations. The corporate tax framework covers locally owned companies, foreign-owned businesses, and branches of international corporations operating in…
-
Understanding Corporate Income Tax in Liberia

Liberia operates a self-assessment tax system, requiring businesses to calculate, report, and pay their corporate income taxes annually. Both resident and non-resident companies earning taxable income in Liberia are subject to the country’s tax regulations. Corporate Income Tax Rates in Liberia The standard corporate income tax (CIT) rate in Liberia is 25%. However, businesses operating…