
International expansion can create significant commercial opportunities, but it also introduces accounting, reporting, control and compliance obligations that require disciplined preparation. Businesses entering new jurisdictions must adapt not only their operating model, but also the financial governance framework that supports decision-making, statutory compliance and audit assurance.
For finance leaders, the priority should be to establish a scalable reporting and control environment before international operations become too complex to manage efficiently. Differences in accounting standards, tax rules, currencies, statutory obligations and audit requirements can quickly create inconsistencies if responsibilities are unclear or local practices develop without adequate group oversight.
A well-designed international finance framework should therefore combine local regulatory compliance with consistent group accounting policies, strong internal controls and reliable consolidated reporting.
Assess the Applicable Accounting Framework Before Market Entry
Before establishing operations in a new jurisdiction, management should determine the accounting and financial reporting framework that will apply to the local entity.
A group may prepare consolidated financial statements under International Financial Reporting Standards while individual subsidiaries are required to prepare statutory accounts under local accounting standards or another permitted framework. In some jurisdictions, sector-specific requirements may also apply to regulated businesses.
These differences can create additional reconciliation and conversion requirements at reporting dates.
For example, a Ghana-based group establishing operations in Kenya, South Africa and the United Arab Emirates may need to consider differences in statutory reporting, disclosure requirements and local accounting treatments. Even where IFRS is commonly applied, local filing requirements and regulatory interpretations may not be identical.
Management should document these differences through a formal accounting framework matrix covering each jurisdiction. The matrix should identify the statutory reporting basis, filing deadlines, audit requirements, local reporting obligations and any recurring adjustments required for group consolidation.
This exercise should form part of the market-entry process rather than being postponed until the first year-end audit.
Standardize Group Accounting Policies Across All Entities
International growth increases the risk of inconsistent accounting treatment across subsidiaries. This is particularly common where local finance teams operate independently or where commercial arrangements vary between markets.
Revenue recognition is one of the areas that frequently requires closer review. A business may sell products directly in one country, operate through distributors in another and provide bundled services in a third. Although the underlying business may be similar, contractual differences can affect the timing and measurement of revenue.
Similar inconsistencies may arise in areas such as inventory valuation, lease accounting, capitalization of development expenditure, provisions, impairment, expected credit losses and employee benefits.
A formal group accounting manual should therefore be established and applied consistently across all entities. The manual should clearly explain the accounting treatment for material transaction categories and define when local finance teams must escalate complex or unusual matters to group finance.
Regular technical training should also be provided to ensure that accounting policies remain consistently understood as the business expands.
Consistency is particularly important during consolidation, where relatively small differences in local accounting practices can create significant adjustments across multiple entities.
Establish a Clear Foreign Currency Accounting Policy
Foreign currency accounting should be treated as a core area of financial control for any group operating across multiple jurisdictions.
Each subsidiary must have an appropriately determined functional currency based on the economic environment in which it primarily generates and spends cash. This determination should reflect the underlying commercial substance of the entity rather than simply the currency in which its bank account is maintained.
Management should also define approved exchange-rate sources and establish consistent rules for translating income statement items, balance sheet balances, intercompany transactions and foreign operations into the group reporting currency.
Without standardization, subsidiaries may use different exchange rates or translation methodologies, resulting in unexplained movements in intercompany balances, foreign exchange gains and losses, or other comprehensive income.
A group-level foreign currency policy should therefore specify the approved exchange-rate source, translation methodology, treatment of monetary and non-monetary items, and procedures for reconciling intercompany foreign currency balances.
Foreign exchange differences should be reviewed regularly rather than being investigated only during the year-end audit.
Strengthen Internal Controls as Operations Expand
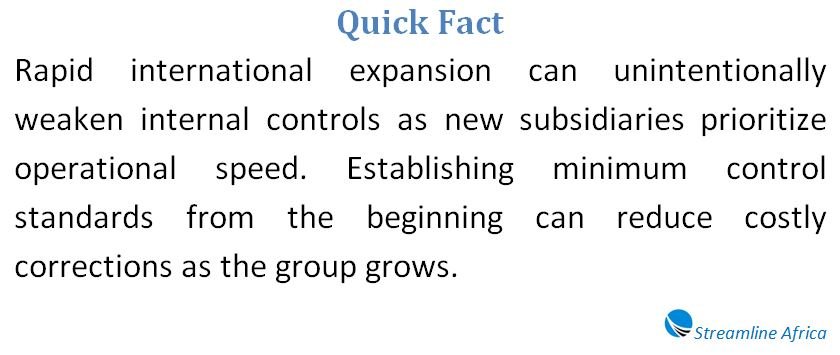
Rapid international growth can place significant pressure on internal controls, particularly in newly established subsidiaries.
Early-stage operations often operate with small teams, which can make segregation of duties difficult. In some cases, the same employee may initiate payments, record transactions and perform reconciliations. While this may appear practical from a staffing perspective, it creates avoidable control risk.
International operations may also face greater pressure to accelerate procurement, establish suppliers quickly or meet ambitious revenue targets. These pressures can increase the risk of management override or informal exceptions to established procedures.
Businesses should define minimum control requirements that apply across all jurisdictions regardless of entity size.
These controls should include approval limits, independent bank reconciliation reviews, controlled system access, supplier onboarding procedures, payment authorization requirements, payroll review controls and periodic financial management reviews.
Where full segregation of duties is not practical, compensating controls should be introduced. Group finance may, for example, independently review high-value payments, supplier master-file changes, bank reconciliations and unusual journal entries.
Control design should be proportionate to the risk profile of each operation, but minimum governance standards should remain consistent throughout the group.
Build Local Regulatory Compliance Into the Operating Model
International expansion should not be approached on the assumption that domestic compliance practices can simply be transferred into another jurisdiction.
Each country has its own requirements relating to taxation, payroll, employment law, company registration, corporate governance, statutory reporting and record retention.
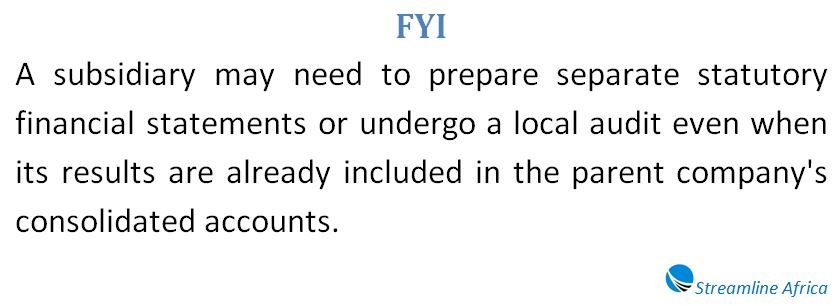
A subsidiary may be required to prepare standalone financial statements, maintain specific accounting records locally, submit periodic regulatory returns or undergo a statutory audit even where its financial results are consolidated into the parent company’s accounts.
Tax obligations may include corporate income tax, withholding tax, value-added tax, payroll taxes, customs duties and transfer pricing requirements. Cross-border service fees, royalties, intercompany loans and management charges may also create additional reporting and documentation obligations.
Management should obtain appropriate local legal, tax and accounting advice before operations commence.
A compliance calendar should then be maintained for each entity, covering statutory filing deadlines, tax submissions, audit requirements, licence renewals and other recurring obligations.
Responsibility for each compliance activity should be clearly assigned, with appropriate oversight from group finance or legal functions.
Enhance Controls Over Third Parties and Integrity Risks
Expansion into unfamiliar markets often increases reliance on distributors, agents, customs brokers, consultants and other third parties.
These relationships may expose the business to bribery, corruption, fraud and reputational risks if appropriate due diligence is not performed.
Particular attention should be paid to high commissions, unusual consulting arrangements, facilitation-related expenses, payments to intermediaries and transactions involving public officials or politically exposed persons.
Third-party onboarding should include documented due diligence, conflict-of-interest checks, ownership verification and appropriate approval procedures.
Payments should be supported by clear contracts, evidence of services received and transparent invoicing.
Businesses should also establish accessible reporting channels through which employees and business partners can raise concerns about suspected misconduct.
International expansion should not result in different ethical standards being applied in different locations. Group compliance expectations should remain consistent regardless of local market practices.
Adapt Audit Planning to the International Structure
As a business becomes more geographically dispersed, the audit process becomes more complex and resource intensive.
Audit planning should identify which entities are financially significant, which locations present elevated risks and where specialist support may be required.
Local tax specialists, valuation experts, information technology auditors or component auditors may need to participate depending on the nature of the business.
New subsidiaries often present heightened audit risk because they may have limited operating history, developing controls and less experienced finance teams. Auditors may therefore perform additional procedures around revenue, cash, inventory, intercompany transactions, management estimates and regulatory compliance.
Where local audit firms perform work on subsidiaries, appropriate coordination between the group auditor and component auditors is essential. Scope, materiality, reporting expectations and timelines should be communicated clearly.
Management should also anticipate that obtaining audit evidence from multiple jurisdictions can take longer than expected.
Audit readiness should therefore begin well before year-end.
Coordinate Statutory and Group Reporting Timelines
International groups frequently operate with multiple reporting deadlines.
A subsidiary may have a local statutory reporting requirement that falls before or after the group’s consolidated reporting deadline. If these timelines are not coordinated, local audit adjustments may emerge after consolidated accounts have already been substantially completed.
Management should develop an integrated reporting calendar that links monthly closes, year-end reporting, statutory accounts, local audits, group consolidation and tax filings.
Subsidiaries should also be required to complete intercompany reconciliations before reporting submissions are finalized.
Unreconciled differences involving management fees, inventory transfers, loans or shared-service charges should be investigated promptly.
Subsequent events and going-concern considerations should also be reviewed at both subsidiary and group level.
For example, regulatory restrictions, currency controls, litigation, financing challenges or major customer defaults in one jurisdiction may have implications for the wider group.
Invest in Scalable Finance Infrastructure
International expansion becomes more manageable when finance infrastructure grows alongside commercial operations.
Businesses should establish standardized reporting templates, chart-of-account structures, accounting policies, control procedures and reporting calendars across all entities.
Where practical, financial systems should be integrated or configured to support consistent reporting across jurisdictions.
Centralized enterprise resource planning systems, consolidation tools and automated reporting solutions can improve visibility and reduce manual reconciliation work. However, technology should support a clearly defined governance framework rather than replace it.
Responsibilities between local finance teams and headquarters should also be documented.
Local teams should understand which matters they are authorized to resolve independently, which transactions require group approval and which technical issues must be escalated.
Treat Financial Governance as Part of the Expansion Strategy
The most effective international expansion strategies integrate finance, compliance and audit considerations from the beginning.
Businesses that enter new markets without structured accounting policies, local compliance planning or adequate controls often spend significant time correcting inconsistencies later. These problems may lead to delayed reporting, unexpected audit adjustments, regulatory penalties or unreliable management information.
Finance leaders should therefore assess accounting standards, foreign currency exposure, tax obligations, internal controls, statutory reporting and audit requirements before launching significant operations in a new jurisdiction.
Strong financial governance provides more than compliance protection. It creates a consistent foundation for decision-making, improves the reliability of group reporting and gives management greater visibility over performance across markets.
For organizations pursuing sustained international growth, the objective should be clear: commercial expansion and financial governance must develop together. A scalable accounting and control framework enables businesses to enter new markets with greater confidence while maintaining transparency, accountability and reporting integrity.
Important Questions and Answers
Why should accounting be considered before entering a new country?
Accounting requirements can differ significantly between jurisdictions. Reviewing them before expansion helps a business avoid reporting errors, unexpected compliance costs and major adjustments after operations have already begun.
Can a multinational company use the same accounting standards everywhere?
Not always. A group may use IFRS for consolidated reporting while individual subsidiaries must comply with local statutory standards. This can require reconciliations or adjustments before subsidiary results are consolidated.
How can businesses maintain consistent accounting across international subsidiaries?
A group accounting manual is essential. It should establish common policies for areas such as revenue recognition, inventory, leases, impairment, provisions and intercompany transactions while defining when complex matters should be escalated.
Why is foreign currency accounting a major concern?
International businesses may transact and report in several currencies. Incorrect functional currency assessments, inconsistent exchange rates or poor translation procedures can distort profits, intercompany balances and foreign currency reserves.
What internal control problems commonly arise during international expansion?
New subsidiaries often begin with small teams, making segregation of duties difficult. Businesses should establish minimum group-wide controls and introduce compensating reviews where employees cannot perform fully separated roles.
Does complying with home-country regulations cover foreign operations?
No. Each jurisdiction may have different rules covering taxation, payroll, employment, corporate governance, statutory reporting and audits. Local compliance requirements should therefore be assessed separately for every market.
Why should businesses scrutinize agents and other third parties?
International expansion can increase dependence on consultants, distributors, customs brokers and intermediaries. Proper due diligence and payment controls help reduce exposure to fraud, bribery, conflicts of interest and reputational damage.
How does international expansion affect the external audit?
Audits become more complex as operations spread across jurisdictions. Auditors may need local specialists, component auditors, additional risk procedures and more time to obtain evidence and coordinate statutory and group reporting deadlines.
What is the most important financial principle for sustainable international expansion?
Finance infrastructure should grow alongside commercial operations. Accounting policies, internal controls, reporting systems, compliance calendars and audit readiness should be built into the expansion strategy rather than introduced after problems emerge.