
One of the most important starting points in evaluating an individual’s tax position in Kenya is determining residency status. Residency directly influences the scope of income that may be brought within the Kenyan tax system.
Resident individuals are generally taxable on employment income arising from services performed both in Kenya and outside the country. They may also be liable to Kenyan tax on other income that accrues in or is derived from Kenya. This creates a broader tax exposure for residents, particularly for executives, professionals, consultants, and individuals with cross-border income arrangements.
Non-residents, by comparison, are generally taxed only on income that arises from or is sourced within Kenya. For internationally mobile employees and foreign investors, correctly establishing tax residence and the source of income is therefore essential before determining the applicable liability.
How Personal Income Tax Rates Apply
Kenya uses a progressive personal income tax structure. In our advisory work, we often emphasise that progressive taxation does not mean an individual’s entire income is taxed at the highest rate they reach. Instead, different portions of taxable income are subject to different tax percentages.
Under the rates applicable from 1 July 2023, the first KES 288,000 of annual taxable income is taxed at 10%. The next KES 100,000 attracts a rate of 25%, while the following KES 5,612,000 is taxed at 30%.
The next KES 3,600,000 falls within the 32.5% tax band. Any taxable income exceeding KES 9,600,000 is subject to the highest marginal rate of 35%.
For taxpayers, understanding these bands is important when evaluating remuneration packages, bonuses, investment income, and other taxable earnings. Proper tax planning should focus on total tax exposure rather than simply looking at the highest applicable marginal rate.
Personal Relief Available to Residents
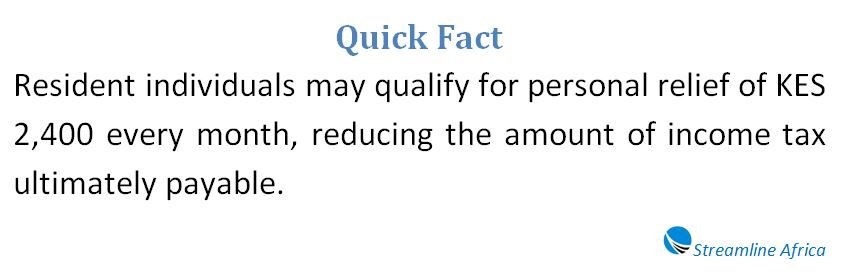
Resident taxpayers are entitled to personal tax relief of KES 2,400 per month. Over a full year, this represents relief of KES 28,800, assuming the taxpayer qualifies throughout the relevant period.
From a payroll and compliance perspective, this relief is particularly important for employees taxed through the Pay As You Earn system. Employers should ensure that qualifying relief is correctly considered when determining monthly PAYE deductions.
For individuals reviewing payslips or annual tax computations, confirming that applicable personal relief has been properly recognised can help identify payroll errors and prevent unnecessary overpayment of tax.
Residential Rental Income Tax for Resident Landlords
Residential property owners represent another category of taxpayers requiring careful attention. Kenya operates a simplified residential rental income tax regime for qualifying resident landlords.
The regime generally applies where annual gross residential rental income does not exceed KES 15 million. Instead of calculating taxable rental profit after deducting expenses, eligible landlords are taxed on their gross rental receipts.
The applicable rate is 7.5%, effective from 1 January 2024. Because the tax is imposed on gross income, landlords cannot deduct expenses such as repairs, property management fees, maintenance expenditure, interest costs, or other property-related expenses when computing liability under this regime.
From an advisory standpoint, landlords should therefore evaluate whether the simplified system produces an appropriate tax outcome based on their income and expenditure profile.
Monthly Filing and Tax Payment Requirements
Eligible landlords are expected to account for residential rental income tax every month through the i-Tax platform. The return and corresponding payment are generally due by the twentieth day of the month following receipt of the rental income.
This monthly compliance requirement makes accurate recordkeeping particularly important. Landlords should maintain reliable schedules of rent received, outstanding amounts, tenant payments, and supporting documentation.
A qualifying landlord may also elect to be taxed under the ordinary income tax framework rather than the simplified residential rental regime. Such an election must be made in writing to the Commissioner. Once approved, the taxpayer becomes subject to normal filing requirements and applicable instalment tax obligations.
Role of Rental Income Tax Agents
Kenya has expanded its rental tax enforcement framework by empowering the Commissioner to appoint rental income tax agents.
These appointed agents may collect and remit rental income tax on behalf of taxpayers. From a compliance perspective, this development reflects increasing administrative focus on the property sector and reinforces the need for landlords to maintain accurate tax records.
Property owners should therefore understand whether any appointed third party is involved in collecting or remitting tax relating to their rental income and should reconcile such payments against their own tax records.
Tax Considerations for Non-Resident Property Owners
The Finance Act, 2026 introduced a final non-resident rental income tax framework for persons deriving income from immovable property located in Kenya.
Non-resident property owners falling within this regime are required to register through a simplified registration process and account for the relevant tax by the twentieth day of the month following the month to which the rental payment relates.
However, the requirement does not apply in the same manner where a resident person receives the rental income on behalf of the non-resident and the payment is already subject to the relevant withholding tax provisions.
For foreign property investors, determining who receives the rent, how payments are structured, and which collection mechanism applies is therefore critical.
Our Advisory Perspective on Individual Tax Compliance
In our experience, personal tax compliance in Kenya extends beyond calculating PAYE or applying published tax rates. Individuals should consider residency, income sources, reliefs, rental receipts, filing deadlines, and cross-border arrangements as part of a broader tax position.
Employees, landlords, expatriates, investors, and high-income individuals may face different reporting responsibilities depending on their circumstances. We therefore recommend periodic reviews of personal tax exposure, particularly where income sources change or cross-border transactions are involved.
A structured approach to tax planning, accurate documentation, and timely filing can reduce exposure to penalties, minimise compliance risks, and help taxpayers make more informed financial decisions.
FAQs about Personal Income Tax in Kenya
Who is generally required to pay personal income tax in Kenya?
Both residents and non-residents may have Kenyan income tax obligations. Residents generally face broader taxation, while non-residents are mainly taxed on income arising from or sourced in Kenya.
How are resident individuals taxed in Kenya?
Resident individuals may be taxed on employment income connected with services performed in Kenya or abroad, as well as other qualifying income that accrues in or is derived from Kenya.
How are non-residents taxed differently?
Non-residents are generally taxed only on income earned, accrued, or derived from Kenyan sources, making income sourcing particularly important for foreign professionals and investors.
What is the highest personal income tax rate in Kenya?
The top marginal personal income tax rate is 35%, applying to annual taxable income above KES 9.6 million.
Does the highest tax rate apply to all of a high earner’s income?
No. Kenya uses progressive tax bands, so only the portion of income falling within the highest bracket is taxed at 35%.
What personal tax relief is available to residents?
Qualifying resident individuals are entitled to personal relief of KES 2,400 per month, equivalent to KES 28,800 for a full year.
What is residential rental income tax?
It is a simplified taxation system for qualifying resident landlords earning income from residential property situated in Kenya.
What is the residential rental income tax rate?
Qualifying residential rental income is taxed at 7.5% of gross rental receipts under the simplified regime.
Can landlords deduct property expenses under the simplified rental tax regime?
No. Because the tax is calculated on gross rental income, expenses such as repairs, management costs and maintenance are generally not deducted.
When must residential rental income tax be filed and paid?
Eligible landlords generally need to file and pay the tax by the 20th day of the month following the month in which the rent was received.
Can a landlord choose the normal income tax system instead?
Yes. A qualifying landlord may apply in writing to the Commissioner to be taxed under the ordinary income tax framework instead of the simplified rental regime.
What should non-resident property owners understand about rental taxation?
Non-residents earning income from immovable property in Kenya may fall under the final non-resident rental income tax framework introduced in 2026, subject to specific registration, payment and withholding rules.