

Uganda’s personal income tax system determines how individuals are taxed based on their earnings, residency status, and sources of income. Residents generally pay tax on income earned both within Uganda and abroad, while non-residents are taxed only on income originating from Uganda.
Taxable income is calculated after accounting for deductions permitted under the country’s income tax laws. The amount an individual pays depends largely on their annual earnings and the tax bracket into which those earnings fall.
Read Also: Uganda’s Investment and Commercial Landscape
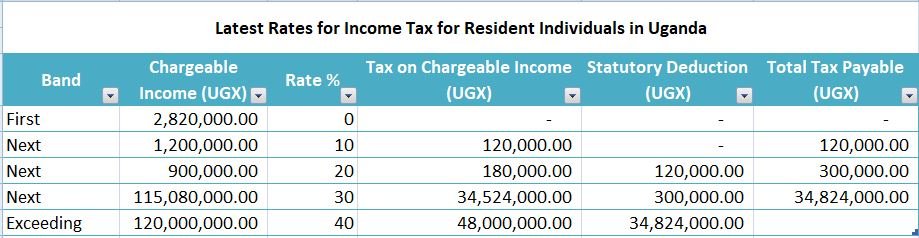
Personal Income Tax Rates for Residents
Uganda follows a progressive tax system, meaning individuals with higher incomes pay higher rates on the portions of their earnings that fall within the relevant tax brackets.
Residents earning up to UGX 2,820,000 annually are exempt from personal income tax. Higher earnings attract rates ranging from 10% to 40%, depending on the applicable income band.
| Annual Taxable Income (UGX) | Tax Payable |
|---|---|
| 0 – 2,820,000 | 0% (Tax-Free) |
| 2,820,001 – 4,020,000 | 10% of income above UGX 2,820,000 |
| 4,020,001 – 4,920,000 | UGX 120,000 + 20% of income above UGX 4,020,000 |
| 4,920,001 – 120,000,000 | UGX 300,000 + 30% of income above UGX 4,920,000 |
| Above 120,000,000 | UGX 34,824,000 + 40% of income above UGX 120,000,000 |
These rates apply to different portions of taxable income rather than the individual’s entire earnings.
Personal Income Tax Rates for Non-Residents
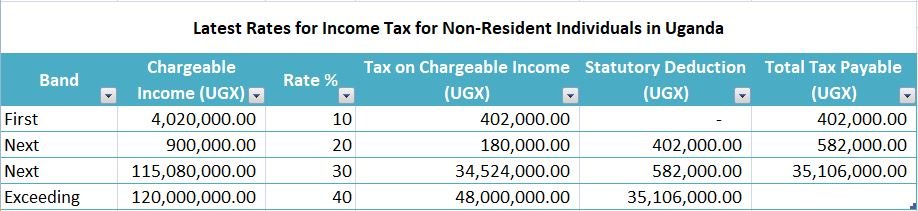
Non-residents are subject to a different tax structure, particularly at the lower income levels. Unlike residents, they do not benefit from the initial tax-free threshold.
Their annual taxable income is assessed using the following rates:
| Annual Taxable Income (UGX) | Tax Payable |
|---|---|
| 0 – 4,020,000 | 10% of taxable income |
| 4,020,001 – 4,920,000 | UGX 402,000 + 20% of income above UGX 4,020,000 |
| 4,920,001 – 120,000,000 | UGX 582,000 + 30% of income above UGX 4,920,000 |
| Above 120,000,000 | UGX 35,106,000 + 40% of income above UGX 120,000,000 |
How Rental Income Is Taxed
Individuals earning rental income from properties in Uganda are subject to a separate tax obligation.
Rental income attracts a 12% tax on annual gross receipts exceeding UGX 2,820,000. Property owners cannot deduct expenses such as repairs, maintenance, insurance, or property management fees when calculating this tax.
Withholding Tax on Salaries and Investment Income
Employers must deduct the appropriate income tax from employees’ salaries and remit it to the tax authorities. For employees without additional taxable income, these deductions generally settle their employment income tax obligations.
Investment earnings also attract withholding tax. Interest income is generally taxed at 15%, while ordinary dividends attract the same rate. Dividends received from listed companies qualify for a reduced withholding rate of 10%.
Interest earned from government securities receives special treatment, as the applicable withholding tax is final and cannot be claimed as a tax credit.
Withholding Tax on Imports and Government Payments
Individuals importing goods into Uganda generally face withholding tax of 6% on the value of their imports. Maintaining proper payment records helps taxpayers account for amounts already withheld.
A similar 6% withholding requirement applies to qualifying payments exceeding UGX 1 million from government institutions, local authorities, and designated withholding agents.
Where permitted, withholding taxes already paid may be credited against an individual’s final income tax liability, helping prevent duplicate taxation.
Summary of Other Applicable Tax Rates
The following table provides a quick reference to other important taxes affecting individuals in Uganda.
| Income or Transaction Type | Applicable Tax Rate |
|---|---|
| Individual rental income | 12% on annual gross rental income above UGX 2,820,000 |
| Interest income | 15% |
| Ordinary dividend income | 15% |
| Dividends from listed companies | 10% |
| Import withholding tax | 6% |
| Qualifying government and designated withholding-agent payments | 6% on payments exceeding UGX 1 million |
Understanding these tax obligations can help employees, property owners, investors, and individuals conducting business in Uganda manage their finances more effectively and meet their responsibilities under the country’s tax laws.