
Senegal’s progressive personal income tax system considers an individual’s earnings, residency status, and family circumstances. Residents generally face taxation on worldwide income, while employment income may attract Senegalese tax when duties are performed locally or remuneration originates from an employer established in the country.
For professionals working in Dakar, Thiès, or Saint-Louis, understanding these obligations is essential for effective financial planning and regulatory compliance.
Personal Income Tax Rates and Family Allowances
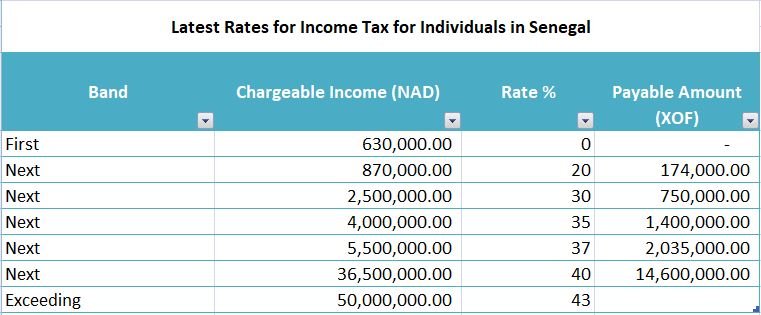
Senegal calculates personal income tax using progressive rates ranging from 0% to 43%. The assessment incorporates a family quotient mechanism, allowing qualifying taxpayers to divide taxable income into shares reflecting their personal circumstances.
Tax is initially calculated against each share before multiplication by the applicable number of shares.
Annual taxable income attracts the following rates:
| Annual Income (XOF) | Tax Rate |
|---|---|
| 0–630,000 | 0% |
| 630,001–1,500,000 | 20% |
| 1,500,001–4,000,000 | 30% |
| 4,000,001–8,000,000 | 35% |
| 8,000,001–13,500,000 | 37% |
| 13,500,001–50,000,000 | 40% |
| Above 50,000,000 | 43% |
Minimum Personal Income Tax Requirements
Employees must also account for minimum personal income tax, determined according to annual earnings.
| Annual Income (XOF) | Minimum Tax (XOF) |
|---|---|
| Below 600,000 | 900 |
| 600,000–999,999 | 3,600 |
| 1,000,000–1,999,999 | 4,800 |
| 2,000,000–6,999,999 | 12,000 |
| 7,000,000–11,999,999 | 18,000 |
| 12,000,000 and above | 36,000 |
Employers should incorporate these requirements into payroll administration to maintain accurate employee tax deductions.
Withholding Tax on Professional Services
Payments to qualifying resident service providers generally attract 5% withholding tax. This applies particularly to small operators under simplified taxation, unregistered providers, and certain tax-transparent businesses.
For example, a manufacturing enterprise in Kaolack engaging an eligible independent technician must deduct the applicable withholding amount before settlement.
The deducted tax must reach the authorities within 15 days following the payment month.
Payments to foreign providers require separate assessment under applicable corporate withholding provisions and international tax agreements.
Rental Income and Property Withholding
Rental payments to individual landlords generally attract 5% withholding tax. However, exemptions apply where monthly rent falls below XOF 150,000, qualifying corporate landlords receive payment, or individuals remit rent through property agencies.
Applicable deductions require timely remittance, alongside quarterly and annual reporting.
Taxation of Investment and Financial Returns
Senegal imposes withholding taxes on several investment income categories, subject to treaty relief and statutory exemptions.
Dividend distributions attract 10%, bond interest 13%, qualifying bank deposit interest 8%, and other interest income generally 16%.
Businesses, banks, and investors should monitor payment deadlines carefully, as different financial income categories carry distinct remittance schedules and compliance responsibilities.
Frequently Asked Questions About Personal Income Tax in Senegal
What Are the Personal Income Tax Rates in Senegal?
Senegal applies progressive personal income tax rates ranging from 0% to 43%. Higher taxable earnings attract higher rates, with the maximum rate applying to annual income exceeding XOF 50 million.
Is There a Tax-Free Income Threshold in Senegal?
Yes. Under the progressive tax schedule, the first XOF 630,000 of annual taxable income falls within the 0% bracket. However, employees may still be subject to minimum personal income tax.
How Does Family Size Affect Personal Income Tax?
Senegal uses a family quotient system that considers qualifying family circumstances. Taxable income is divided into applicable shares, potentially reducing the overall tax burden for eligible taxpayers.
What Is the Minimum Personal Income Tax in Senegal?
Minimum personal income tax is an employee tax obligation determined by annual earnings. It ranges from XOF 900 to XOF 36,000, depending on the employee’s income category.
Are Freelancers and Independent Contractors Subject to Withholding Tax?
Yes. Certain payments to resident freelancers, small business operators, and independent service providers attract 5% withholding tax, depending on their registration and tax status.
Does Senegal Apply Withholding Tax on Rental Income?
Yes. Rental payments to individual property owners generally attract 5% withholding tax. However, exceptions include monthly rents below XOF 150,000 and certain payments involving companies or property agencies.
Read Also: Senegal: Evaluating the Business Landscape, Investment Risks, and Growth Potential
How Are Dividends Taxed in Senegal?
Dividend income generally attracts 10% withholding tax. The distributing company is responsible for applying the deduction, subject to applicable exemptions and double taxation agreements.
What Tax Rates Apply to Interest Income?
Bond interest generally attracts 13%, qualifying bank deposit interest 8%, and other interest income, including certain loan interest payments, 16%.
When Must Withholding Taxes Be Paid to the Authorities?
Withholding taxes on qualifying professional services and rental payments must generally be remitted within 15 days following the payment month. Financial income may follow different payment schedules.