
Latest posts
-
Restricted Cash: Understanding Funds That Businesses Cannot Freely Spend
What Restricted Cash Means in Corporate Accounting Restricted cash represents money that belongs to a business but cannot be used freely for ordinary operating activities. Although the funds remain under the company’s ownership, a legal agreement, contractual obligation, regulatory requirement, or internal commitment limits how and when the money may be spent. This distinction matters…
-
Quality of Earnings Ratio (QoE): Evaluating the Strength Behind Reported Profit
Understanding the Quality of Earnings Ratio A company may report impressive profits, but those figures do not always reflect the amount of cash being generated through its normal business activities. The Quality of Earnings Ratio, commonly called the QoE ratio, helps analysts assess whether reported net income is strongly supported by operating cash flow. The…
-
Operating Working Capital (OWC): Definition, Formula, Analysis and Practical Application
Operating Working Capital (OWC) is a financial management metric used to determine the amount of short-term capital committed to an organisation’s recurring business activities. It provides analysts with a more operationally focused assessment of working capital by concentrating on current assets and current liabilities that arise directly from normal commercial activities. For finance and accounting…
-
Interest Income: Meaning, Formula, Calculation, Examples and Financial Statement Treatment
Interest income represents the earnings generated when a company places available cash or other financial assets in interest-bearing instruments. In practical terms, it is the financial return received for allowing a bank, financial institution, government, or other approved borrower to use the company’s funds for a specified period. For students studying accounting, finance, or financial…
-
Long-Term Debt: Definition, Formula, Examples and Accounting Treatment
Long-term debt represents financial obligations that a company is required to repay over a period extending beyond 12 months. It is an important component of corporate finance and balance-sheet analysis because it shows the extent to which a business relies on external borrowing to support investment, expansion and long-term operating needs. For students conducting research…
-
Deferred Tax Assets: How to Calculate, Record and Use Future Tax Benefits
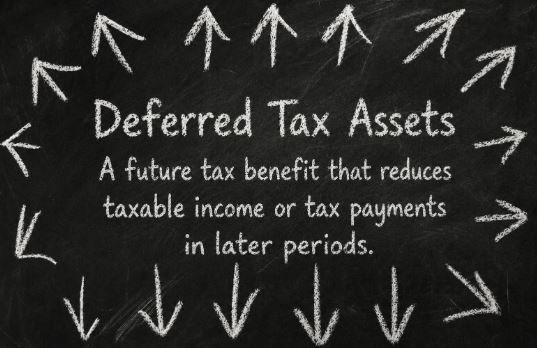
A deferred tax asset represents a future tax advantage that arises when accounting rules and tax rules recognize income, expenses, losses, or deductions at different times. Although the underlying transaction may already have affected a company’s accounts, the related tax benefit may not be available until a later reporting period. For businesses, this distinction matters…
-
Retained Profits: The Hidden Resource That Shapes a Company’s Future
Every successful business reaches a point where it must decide what to do with the money it earns. After paying salaries, suppliers, taxes, operating costs, and any dividends promised to shareholders, there may still be profits left over. These remaining profits can either be distributed to owners or kept within the company to support future…
-
What Credit and Debit Entries Represent in a Balance Sheet
Accounting relies on a structured system that allows businesses to track every financial movement accurately. Among the most important concepts in this system are debit (DR) and credit (CR). While these terms may seem confusing at first, they are fundamental to understanding how financial records are maintained and how balance sheets remain accurate. Debit and…
-
Contra Liability Account: Meaning, Examples, Accounting Treatment, and Financial Statement Impact
A contra liability account is a unique category in accounting that functions opposite to a standard liability account. While most liabilities carry a credit balance and increase obligations on the balance sheet, a contra liability account carries a debit balance and serves to reduce the reported value of a related liability. Understanding how these accounts…
-
What is Adjusted Net Income? A Practical Guide to Measuring True Profitability
Adjusted net income is a profitability measure designed to present a clearer picture of a company’s ongoing earnings by removing items that may distort its financial results. Unlike standard net income, which follows formal accounting rules, adjusted net income attempts to reflect the earnings generated from normal business activities by excluding unusual, one-time, or non-cash…